Yes, you can use a home equity loan on your current home to buy land, and it’s often an easier path than getting a separate land loan. When you take a home equity loan, the lender gives you a lump sum of cash. In most cases, you’re free to use that money however you like, including buying a vacant lot, acreage, or a future building site. The lender’s security is your current home, not the land you’re buying, so they usually don’t restrict the purchase.
This matters because land loans on their own can be tricky. Lenders often see raw land as riskier, so a direct land loan may require a larger down payment and tougher terms. A home equity loan sidesteps that. You get cash up front, buy the land outright as a cash buyer, and skip the separate land-loan process. The trade-off is important, though: your home now secures the debt. If you can’t repay, the home, not the land, is what’s at risk. To see what’s required to qualify, read our guide on home equity lending requirements.
Why Buyers Choose a Home Equity Loan to Buy Land
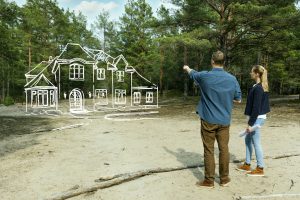
Using home equity to buy land has real advantages.
You become a cash buyer, which can give you stronger footing when making an offer.
You get a single, predictable payment instead of juggling a second specialty loan.
And because a fixed-rate home equity loan has a steady payment, budgeting is simple.
Learn more in our guide on fixed-rate home equity loans.
A Quick Case Study
Consider the Martins, a couple who had paid their mortgage down significantly and had strong equity. They found five acres of country land they hoped to build a retirement home on someday. A direct land loan would have meant a hefty down payment and a short repayment window.
Instead, they took a home equity loan on their current house. The lump sum covered the full price of the land, so they bought it outright with cash. They secured the lot they wanted, locked in one steady monthly payment, and avoided the harder land-loan process. Because they had a clear plan and comfortably afforded the new payment, it was a smart, low-stress way to reach their goal. Their home was appraised first to confirm their available equity — a normal step covered in our guide on whether you need an appraisal for a home equity loan.
Things to Weigh First
Before you borrow, think it through. Raw land usually doesn’t earn income, so you’ll be making payments on something that isn’t paying you back yet. And your home is on the line. Ask yourself whether you can comfortably afford the payment, whether you have a plan for the land, and whether the purchase fits your bigger goals. Used thoughtfully, this can be an affordable way to buy land. Used carelessly, it risks the home you already have.
Takeaway
You can absolutely use a home equity loan to buy land, and for many buyers it’s simpler and more affordable than a standalone land loan. You get cash up front, purchase the land outright, and enjoy one steady payment. Just remember that your home secures the loan, so borrow only what you can comfortably repay and have a clear plan for the property. Compare several lenders, confirm your available equity, and you’ll be in a strong position to make your land purchase happen.
Frequently Asked Questions
Can you use a home equity loan to buy land?
Yes. A home equity loan gives you a lump sum you can generally use for almost any purpose, including buying vacant land or acreage. Because your current home secures the loan, lenders usually don’t restrict how you spend the money. This makes it a popular alternative to a separate land loan, which can be harder to get. You become a cash buyer for the land, with one steady payment. Just remember your home — not the land — is the collateral.
Is a home equity loan or a land loan better for buying property?
It depends on your situation. A home equity loan is often easier and may offer a lower, steadier payment, since it’s secured by your existing home rather than the land. A dedicated land loan keeps your home out of the deal but usually requires a bigger down payment and shorter terms, because lenders view raw land as riskier. If you have strong equity and can comfortably afford the payment, a home equity loan is frequently the simpler path. Compare both before deciding.
What are the risks of using a home equity loan to buy land?
The biggest risk is that your home secures the loan. If you can’t repay, you could lose the house, not just the land. Raw land also usually produces no income while you make payments, so you’re carrying a cost without a return until you build or sell. Property values and plans can change, too. These risks are manageable if you borrow within your budget and have a clear purpose for the land, but they deserve honest thought before you commit.
References
- Consumer Financial Protection Bureau. (2024). What you should know about home equity loans.
- RefiGuide. (2026) Construction Loan Versus Home Equity Line of Credit
Home Equity Mart is not a lender and does not make credit decisions. This article is general education, not financial or legal advice, and does not quote current rates. The case study is illustrative and does not describe specific clients. Verify any lender’s license at NMLS Consumer Access. Equal Housing Opportunity.